5 min read
Choosing a payment gateway stack for mobile apps in the Philippines is not a spreadsheet exercise—it is a risk management exercise. Founders should optimize for successful charges, clean refunds, finance-grade reconciliation, and fraud controls that match how promos and vouchers behave in the real world.
Start with user journeys
List your must-have flows: charge, partial capture, refund, void, payout to partners, and subscription or installment variants. If a provider cannot support your truthfully modeled journey, it is not a fit—no matter how famous the brand.
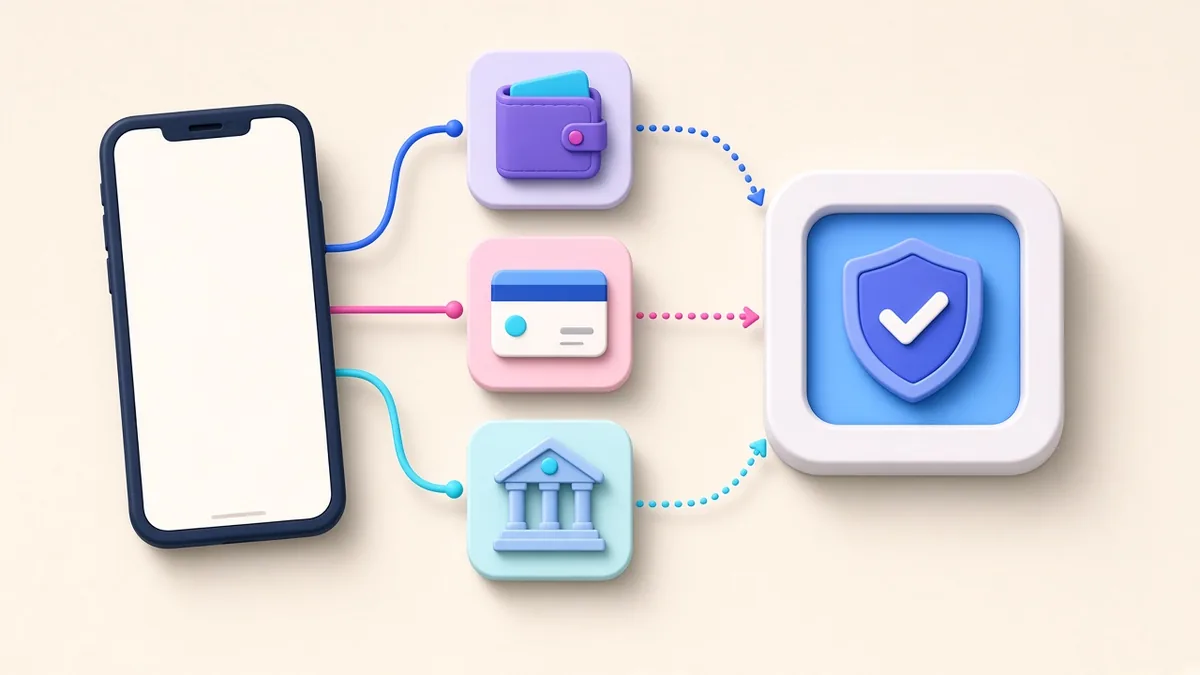
Wallets, cards, and bank redirects
Philippine users split across e-wallets, cards, and bank apps. Your checkout should minimize steps while staying compliant with OTP and step-up authentication requirements.
Subscription and installment pitfalls
If you offer subscriptions, define dunning, proration, and cancellation windows. Installments add lender relationships—scope compliance early.
Cross-border and currency edges
If you touch foreign cards or currencies, model FX and settlement timing explicitly—founders underestimate settlement gaps.
| Method | Typical flow | What to handle |
|---|---|---|
| E-wallets (GCash, Maya) | Redirect or app switch to approve | Abandoned approvals, late webhooks |
| Cards | In-app form or hosted page, often 3-D Secure | Authentication failures, chargebacks |
| Bank redirects / online banking | Redirect to bank | Timeouts, delayed confirmation |
| Installments | Through card issuer or provider | Eligibility, refunds and cancellations |
Reconciliation and money movement
Finance needs settlement files, fee lines, and exception reports. Build admin exports and nightly jobs early—retrofitting accounting discipline after scale is painful.
End-to-end money movement map
Sketch every money movement: user charge, platform fee, partner payout, refunds, chargebacks, and currency handling if relevant. If you cannot draw it, you cannot implement it safely.
Assign owners: product for flows, engineering for idempotency, finance for reconciliation, legal for disclosures. Money touches every function—coordinate deliberately.
Statements and chargebacks
Train support with scripts grounded in card network rules and wallet policies. Inconsistent answers create disputes and social escalations.
Tax and invoice lines
B2B flows may need VAT treatment and invoice identifiers. Model these early—retrofits annoy finance and users.
Reliability: idempotency, load and redundancy
Idempotency and race conditions
Network retries can double-charge if endpoints are not idempotent. Engineers must treat payments like distributed systems—not like buttons.
Load testing payments
Simulate concurrent purchases and refunds in staging. Race conditions appear only under load—find them before users do.
Provider redundancy
Consider failover strategies for critical rails. Outages happen—your UX should degrade gracefully with clear messaging.
Disaster recovery
Document what happens if a PSP is down: can users still place orders? how do you communicate? how do you reconcile partial states?
Fraud, payouts and KYB
Fraud patterns that appear with growth
Voucher farming, card testing, and collusion show up once incentives spike. Implement velocity limits, device signals, and manual review queues proportional to your risk.
Partner payouts and KYB
Marketplaces must pay sellers or drivers on schedules users trust. KYB delays are calendar risks—start paperwork early.
KYB and payout operations
Marketplaces should treat partner onboarding as a funnel: document completion rate, median time-to-first-payout, and drop-off reasons.
Automate reminders for expired IDs and banking changes—manual chasing does not scale.
Reconcile payouts to invoices with exception queues—small mismatches compound monthly.
Security, compliance and monitoring
Security and PCI scope
Minimize PCI scope with hosted fields and tokenization where possible. Security reviews should be part of release gates—not optional extras.
Compliance and disclosure
Work with counsel on receipts, VAT lines, and promotional disclaimers—payment UX is partly legal UX.
Store policies should match in-app copy—contradictions invite disputes.
Observability
Alert on payment failure spikes, increased latency, and elevated review-queue volume—signals often precede user complaints.
Instrumenting payment health
Track authorization rate by rail, device, and corridor. A drop in one segment often signals fraud rule drift or provider issues—not “users changed.”
Segment retries: distinguish user-initiated retries from automatic retries—double charges hide in that ambiguity.
Alert on refund latency spikes—slow refunds generate support load and chargebacks.
Executive dashboards
Weekly leadership view: auth rate, refund rate, chargeback rate, and top failure codes. If leadership reviews revenue without payment health, blind spots grow.
The bottom line
Use hosted fields and network tokens when you can—do not widen PCI scope you cannot defend. Keep retries idempotent, reconcile nightly, and put a human on chargebacks and fraud review when promos spike. If a rail goes down, honest copy beats a timeline you do not control.
Watch auth rate, refund latency, and settlement exceptions. If finance cannot follow your explanation, you are not ready to ship.
Payments are product, finance, and infrastructure at once. Build them with evidence, tests, and reconciliation—not with hope.
Payments are living systems—monitor continuously, reconcile obsessively, and communicate honestly when rails wobble.
Related reading
Pair with Grab-like app cost and on-demand app development Philippines.
Frequently asked questions
Which payment methods should a Philippine app support first?
Usually e-wallets such as GCash and Maya plus cards; add bank and installment options when your customers need them.
What is idempotency in payments?
It means repeating the same request—for example after a timeout—does not charge the customer twice. Use a unique reference per order and check it before processing.
Do I need two payment gateways?
Not at launch for most apps, but plan how you would switch or add a backup provider if one has an outage or changes terms.
